
Correlation Heatmap
Tradeboard Stock Correlation Heatmap Application
Overview
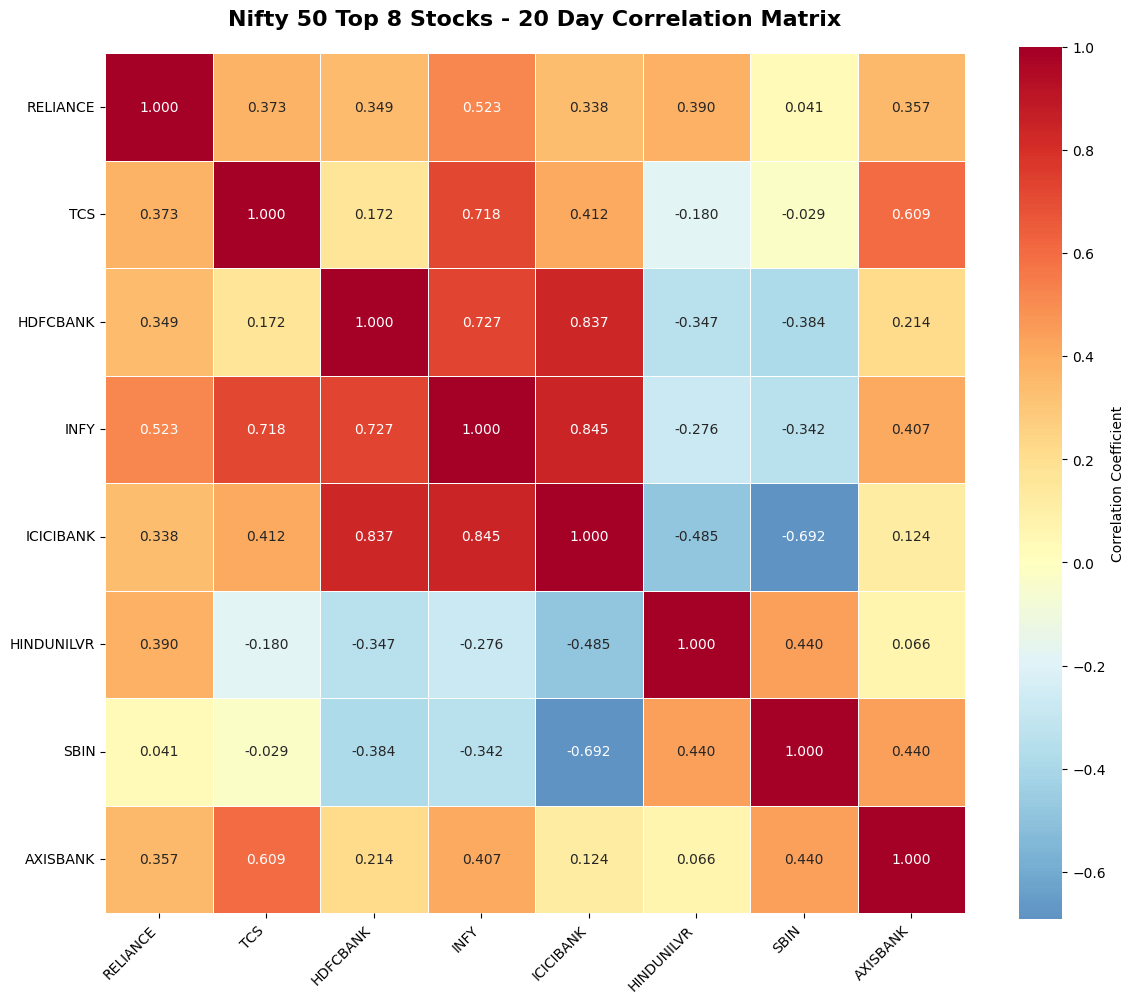
A financial analysis tool that visualizes statistical relationships between India's top 8 Nifty 50 stocks using color-coded correlation heatmaps. Helps traders and portfolio managers identify diversification opportunities and sector clustering patterns.
Prerequisites
- Tradeboard Python SDK:
pip install tradeboard(2.0.3 or higher) - Tradeboard Self-Hosted: Running on
http://127.0.0.1:5000 - Valid API Key: Generated from Tradeboard web interface
- Market Data Access: NSE data permissions
What It Does
Data Analysis
- Fetches daily price data for 8 major stocks (RELIANCE, TCS, HDFCBANK, INFY, ICICIBANK, HINDUNILVR, SBIN, AXISBANK)
- Calculates 20-day rolling correlations between all stock pairs
- Generates symmetric correlation matrix with latest market relationships
python
#!/usr/bin/env python3
"""
Simple Correlation Heatmap - No prints, only visualization
"""

from tradeboard import api, ta
import pandas as pd
import numpy as np
import matplotlib.pyplot as plt
import seaborn as sns
from datetime import datetime, timedelta
import time

def main():
    print("Tradeboard Python Bot is running.")

    # Initialize Tradeboard client
    client = api(
        api_key='your_api_key_here',
        host='http://127.0.0.1:5000'
    )

    # Top 8 Nifty 50 stocks
    nifty_top8 = [
        "RELIANCE", "TCS", "HDFCBANK", "INFY",
        "ICICIBANK", "HINDUNILVR", "SBIN", "AXISBANK"
    ]

    # Date range
    end_date = datetime.now().strftime("%Y-%m-%d")
    start_date = (datetime.now() - timedelta(days=60)).strftime("%Y-%m-%d")

    # Fetch data
    stock_data = {}
    for stock in nifty_top8:
        time.sleep(1)
        try:
            data = client.history(symbol=stock, exchange="NSE", interval="D",
                                start_date=start_date, end_date=end_date)
            data.reset_index(inplace=True)
            stock_data[stock] = data[['timestamp', 'close']].rename(columns={'close': stock})
        except:
            continue

    # Merge data
    merged_data = None
    for stock, data in stock_data.items():
        if merged_data is None:
            merged_data = data
        else:
            merged_data = pd.merge(merged_data, data, on='timestamp', how='inner')

    # Calculate 20-day rolling correlations
    stock_columns = [col for col in merged_data.columns if col != 'timestamp']
    correlation_data = {}

    for i, stock1 in enumerate(stock_columns):
        correlation_data[stock1] = {}
        for j, stock2 in enumerate(stock_columns):
            if i == j:
                correlation_data[stock1][stock2] = 1.0
            else:
                rolling_corr = ta.correlation(merged_data[stock1], merged_data[stock2], period=20)
                latest_corr = rolling_corr.dropna().iloc[-1] if len(rolling_corr.dropna()) > 0 else 0.0
                correlation_data[stock1][stock2] = latest_corr

    # Create correlation matrix
    correlation_matrix = pd.DataFrame(correlation_data)

    # Create heatmap
    plt.figure(figsize=(12, 10))
    sns.heatmap(correlation_matrix, annot=True, cmap='RdYlBu_r', center=0,
                square=True, fmt='.3f', linewidths=0.5,
                cbar_kws={'label': 'Correlation Coefficient'})

    plt.title('Nifty 50 Top 8 Stocks - 20 Day Correlation Matrix',
              fontsize=16, fontweight='bold', pad=20)
    plt.xticks(rotation=45, ha='right')
    plt.yticks(rotation=0)
    plt.tight_layout()
    plt.show()

    return correlation_matrix

if __name__ == "__main__":
    corr_matrix = main()
Visualization
- Creates professional heatmap using color-coded correlation coefficients
- Red colors indicate strong positive correlation (stocks move together)
- Blue colors show weak/negative correlation (stocks move independently)
- Displays exact correlation values on each cell for precise analysis
Key Features
Smart Data Processing
- 60-day lookback for robust correlation calculation
- Rate limiting with 1-second delays between API calls
- Error handling continues analysis if individual stocks fail
- Data alignment ensures all stocks use identical trading dates
Professional Output
- Publication-quality heatmap visualization
- Intuitive color scheme for immediate insight recognition
- Proper labeling with rotated stock symbols
- Statistical annotations showing exact correlation values
Business Applications
Portfolio Management
- Diversification Analysis: Identify low-correlation stocks for risk reduction
- Sector Clustering: Understand which stocks move together
- Risk Assessment: Quantify asset relationships during market events
Trading Insights
- Pairs Trading: Find stocks with stable correlation patterns
- Hedge Selection: Choose assets with negative correlation for hedging
- Sector Rotation: Time market entry based on correlation changes
Interpretation Guide
High Correlation (>0.8)
- Banking stocks (HDFC, ICICI, SBI, AXIS) typically cluster together
- IT stocks (TCS, INFY) often show strong correlation
- Limited diversification benefits
Moderate Correlation (0.4-0.7)
- Related business models with some independence
- Balanced portfolio exposure opportunities
- Sector interconnectedness
Low Correlation (<0.4)
- Strong diversification potential
- Independent price movements
- Risk mitigation opportunities
Technical Approach
Correlation Method
- Uses Tradeboard's
ta.correlation()with 20-day rolling window - Captures current market conditions vs. historical averages
- Updates dynamically with latest price movements
Data Quality
- Validates sufficient data points for meaningful correlation
- Handles missing data gracefully
- Ensures temporal consistency across all assets
Limitations
- Linear relationships only: Doesn't capture non-linear correlations
- Historical bias: Past patterns may not predict future relationships
- Market regime sensitivity: Correlations change during bull/bear markets
- NSE trading hours: Analysis limited to exchange operating sessions
Use Cases
For Portfolio Managers: Optimize asset allocation and reduce concentration risk
For Traders: Identify pair trading opportunities and market relationships
For Risk Analysts: Monitor portfolio correlation exposure and stress test scenarios
For Researchers: Study sector dynamics and market structure relationships
This application transforms complex statistical relationships into actionable investment insights through intuitive visual analysis.